

WTF Was Bessent Thinking?
August 31, 2026 Warsh was as expected – hawkish. This guy cares about inflation as much as I care about the Eagles. But I also think he used the word “hike” 3x in his opening remarks very intentionally.
Odds of a September hike jumped to 60%, but if Powell had given that speech it would be 99%. The market is trying to figure out if Warsh just talks tough or if he is going to push for a hike. Plus, it doesn’t matter since the FOMC needs 7 votes.
Last Week This Morning
-
10T: 4.72%
-
2T: 4.35%
-
SOFR: 3.64%
-
Term SOFR: 3.68%
-
Durable Goods Orders: 1.1% vs 0.5% expected
-
GDP: 1.5% as expected
-
GDP Price Index: 6.4% vs 6.2% expected
-
Inflation came in as expected
-
Core PCE m/m: 0.2% as expected
-
Core PCE y/y: 3.3% as expected
-
-
NFP annual revision: -79k vs +183k expected
-
Fed Speeches
-
Barkin: “At some point, people stop buying your debt and that's the risk out there.”
-
Goolsbee: “I agree with the analysis that the chairman put forth that we’ve been above the target. It was going the wrong way. We’ve gotten a couple of months of more benign readings, but that certainly doesn’t feel like out of the woods.”
-
Warsh: “While this summer’s [inflation] readings were better than expected, they do not tell me that underlying trends have meaningfully improved…We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do. That’s our job, our mandate and our charge to keep.”
-
WTF Was Bessent Thinking?
On August 19th, Scott Bessent announced the Treasury would be doubling the buybacks on the long end of the curve.
First of all, this is not QE. QE is the creation of money. This is more like active debt management. Issue short term debt and use the proceeds to buy long term debt. The outstanding balance doesn’t change.
Also note that the headlines didn’t say Bessent started buybacks…and that’s because Yellen started this program in 2024. Yellen’s purpose was more focused on liquidity than rates. The Treasury would buy oddball off the run Treasurys from primary dealers so they could reinvest that money back into new Treasurys wherever it made the most sense.
Bessent is simply targeting the long end of the curve to bring down long term yields, so this is much more like an Operation Twist than QE.
I hate when the government buys bonds (absent emergencies), but it’s even worse when it’s ineffective. The Treasury has a cash balance of about $1T, but most of that is needed for operations. Bessent can only use the excess cash, which is maybe $300B.
Contrast that with the Fed, which can create money. QE is theoretically unlimited and we know the Fed took it to $9T, or 30x what Bessent can do. That’s why there’s a huge difference between the effectiveness of QE and Treasury buybacks.
Bessent should have known a couple hundred billion wouldn’t have a sustained impact. Now he’s in a staring contest with the market without the keys to the printing press. He can’t win this one.
Deconstructing the Spike in Yields
#1 - Inflation!
Here’s the problem with this argument. The market actually has a pretty basic way to trade this: TIPS. That helps us deconstruct the 10T into two components: inflation component and the real yield component. As you can see, the inflation component (blue) did jump in April and May but has since settled back to levels we saw last year. The real yield (white) has surged dramatically.
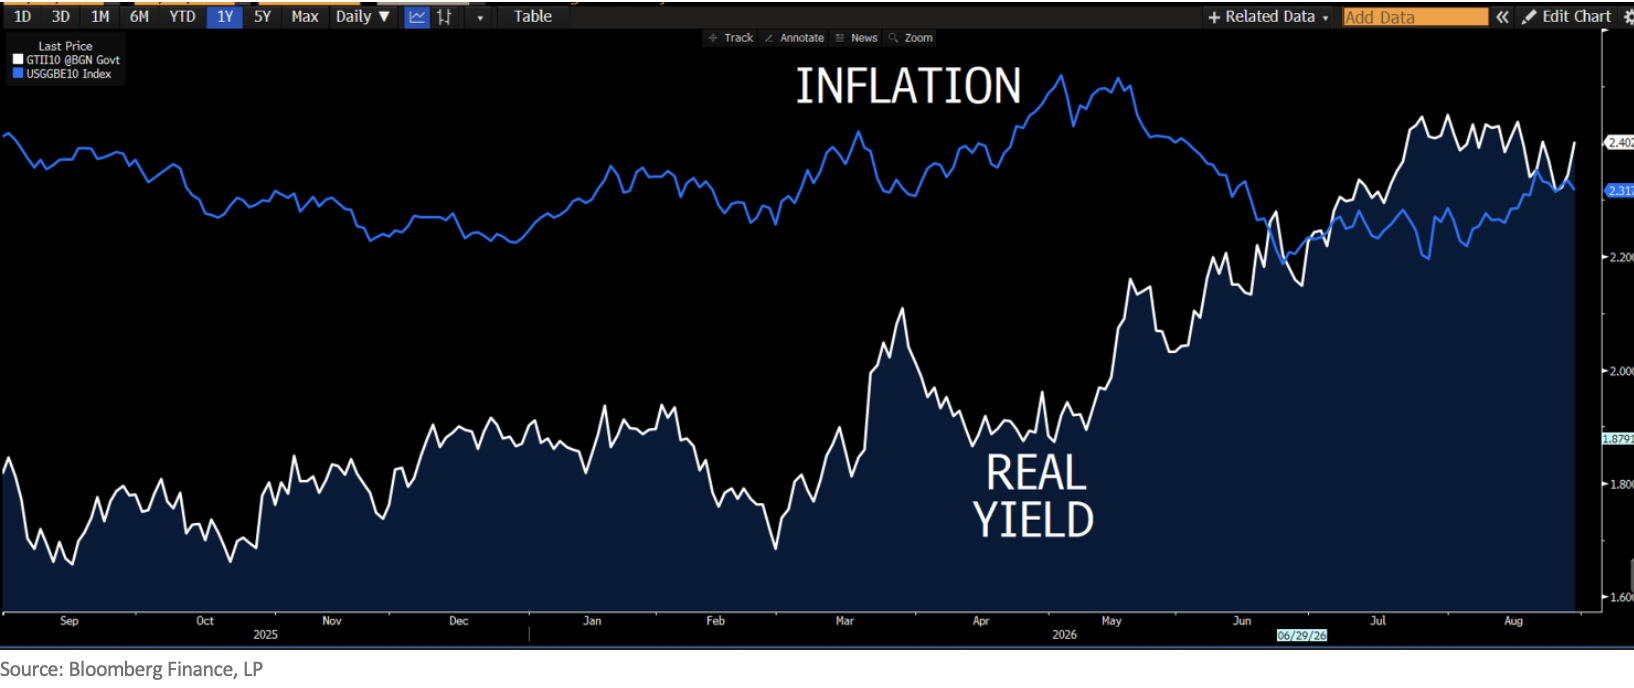
So what would cause real yields to surge?
#2 - The Fed
We started the year expecting 2-3 cuts and now the market expects 2-3 hikes.
The initial jump in front-end yields coincided almost perfectly with the Iran conflict and the spike in oil. Inflation fears rose, but markets also completely repriced the Fed. Rate cuts disappeared and eventually rate hikes entered the conversation. That matters because tighter expected Fed policy shows up primarily in real yields.
Inflation fears have receded, but the Fed is still talking up hikes. Iran inflation may have lit the match, but the Fed's expected response helped turn it into a much larger and persistent move in rates. The easiest place to see this is the 2-year Treasury.
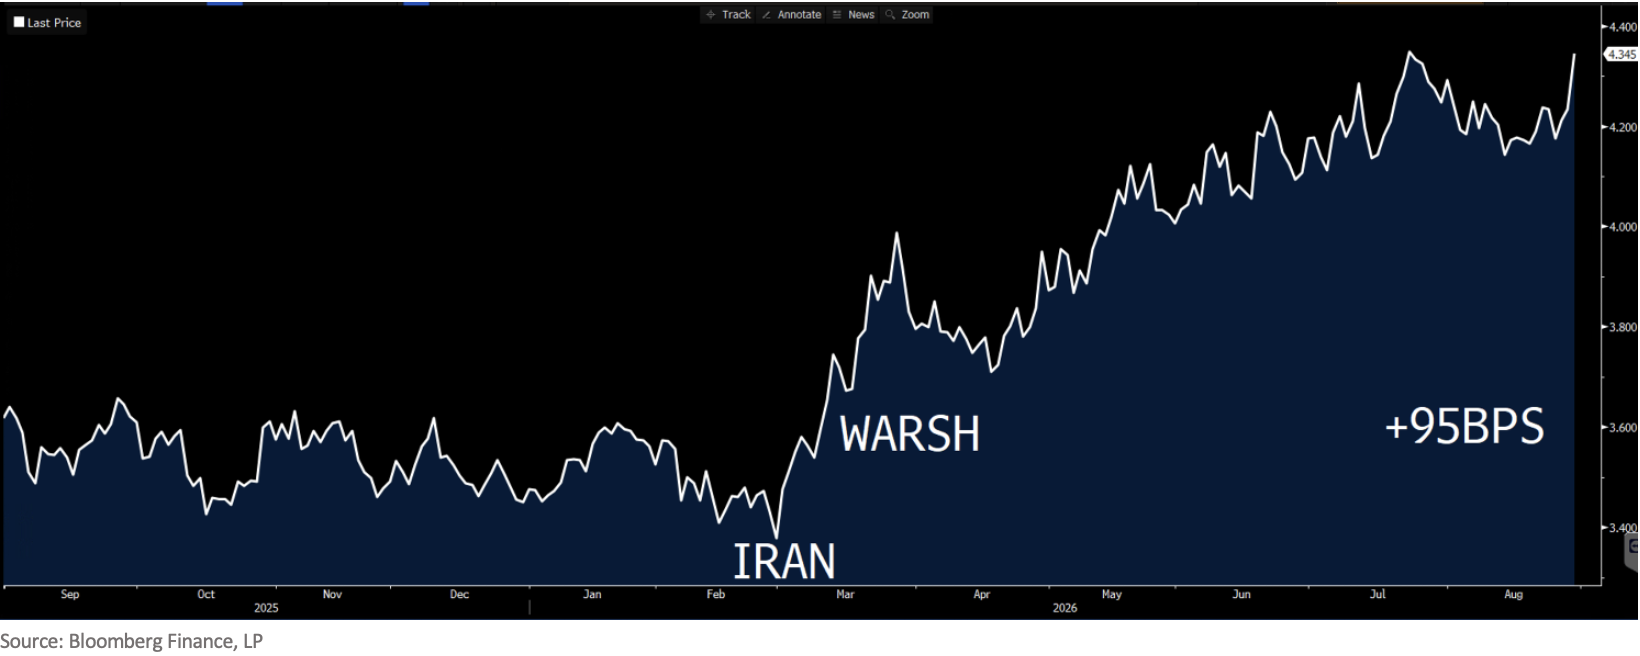
It has risen as much as the 10T. That’s hardly what we would expect if this were simply investors demanding a larger premium because of deficits.
Speaking of which…
#3 - Deficits
Right before he passed away, Alan Greenspan noted, “The federal budget is on an unsustainable path.” A blast at parties right to the end. RIP legend.
“Investors are revolting! The US is bankrupt! Everyone is bailing out of Treasurys!” – a lot of heated emails over the last few weeks.
But why now when we’ve run a deficit every year since 2001? Some of you reading this literally have never seen a budget surplus. Today is suddenly the day the entire world revolts? Maybe…but maybe not.
Deficits clearly matter, but they're hardly new. In fact, that Greenspan quote was from 2005, not June. Why didn’t everything blow up over the last 20 years?
Here’s the budget as a % of GDP, currently a deficit of 6%. Also, be sure to compare the deficit to the size of the economy. Everything’s relative.
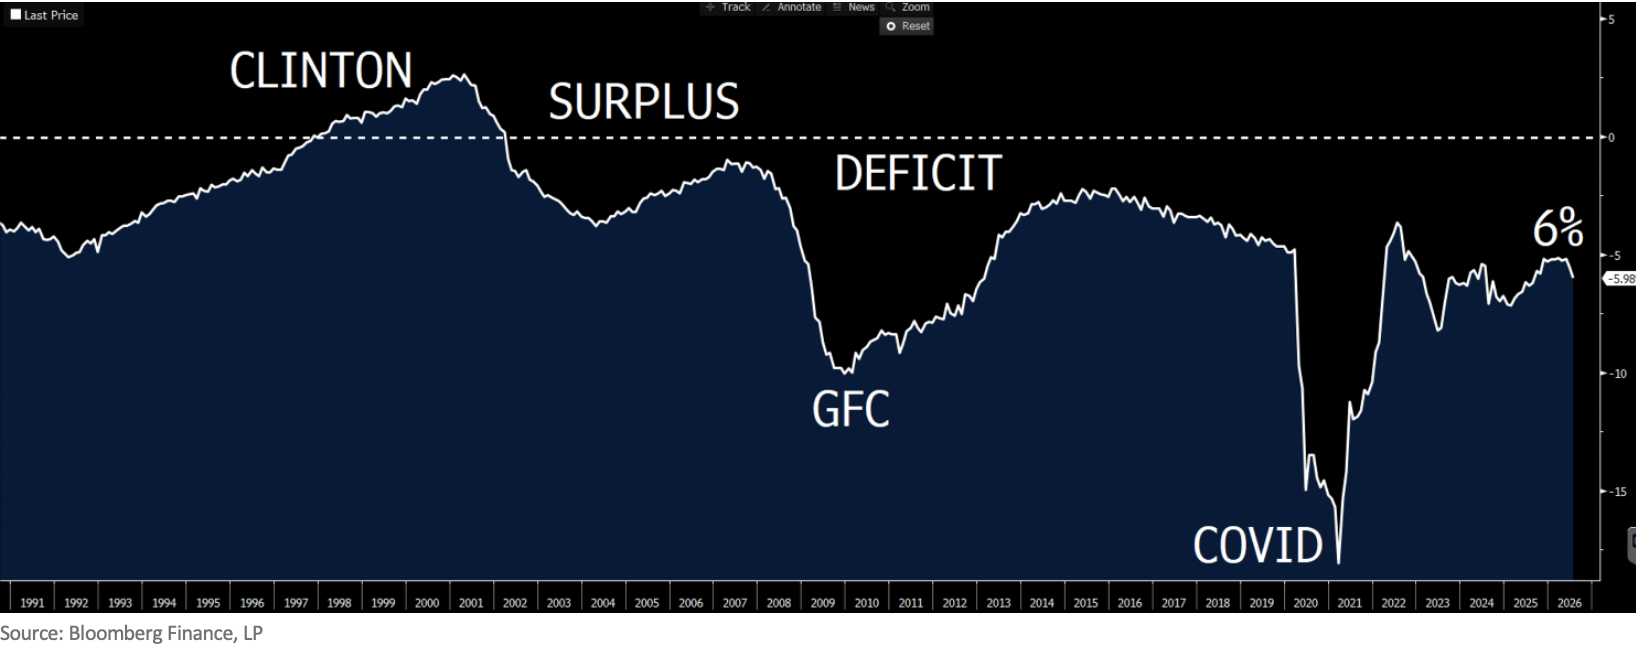
What is unusual today is that we're running a deficit approaching 6% of GDP without a GFC or covid-sized economic emergency. That's a legitimate concern. But that might mean 10bps or 20bps, not 100bps or 200bps.
“Whenever a really bright person who has a lot of money goes broke, it’s because of leverage… it would be almost impossible to go broke without borrowed money being in the equation,” Warren Buffett. The US federal government entered the chat 20yrs ago, maybe markets are finally starting to care.
But it still leaves an important question unanswered: why did the bond market suddenly begin demanding dramatically higher yields in February?
#4 - US Credit Quality in the Toilet
The only people as annoying as the deficit goobers are the ones who scream about how the US credit quality is to blame. “The US is going to default at some point! Corporates are safer than the US!”
Simma down now. US CDS is 33bps, basically the same as the last three years. By way of comparison, Nvidia is 78bps.
Switzerland and Germany CDS are at 7bps, so the market does price the US as somewhat riskier than the absolute safest, but the sky isn’t falling.
Plus, if US credit quality/deficits were the primary culprit, we’d expect US yields to be the outlier. Segue alert…
#5 - This Isn’t Just A US Problem
Yields are up everywhere, not just in the US. As foreign sovereigns offer more attractive yields, Treasurys have to compete harder for global capital.
-
Japanese yields at highest levels since 1995
-
German yields at a 15 year high
-
UK yields at highest level since GFC
-
French yields at highest level since 2008
So part of the move here may simply be higher global yields.
Japan adds a technical wrinkle as yen intervention can create short-term selling or funding pressure.
In Summary
It’s so much more fun when it’s a single thing. “Deficits! Yen intervention! Sovereign debt crisis!” But I just don’t believe that to be the case. Here is an incredibly precise no chance this is wrong guaranteed down to the basis point estimate of how much each factor has contributed to the 75bps run up.
Inflation 5bps
Fed policy 40bps
Deficits 20bps
US credit 0bps
Global/yen 10bps
Total 75bps
And if you want long term yields to come back down, just think about what would reverse each of those.
The Week Ahead
If rate hike odds have contributed 40bps of upward pressure to the 10T, Friday’s jobs report is massive. Remember, last month showed a loss of 23k jobs. This week’s consensus is a gain of 55k.
If this week’s number is negative again, that would be two consecutive months of job losses coupled with two consecutive months of benign inflation.
How could the Fed justify a hike in the face of those conditions?