

Inflation? What Inflation?
August 17, 2026
This feels like an oddly personal attack…
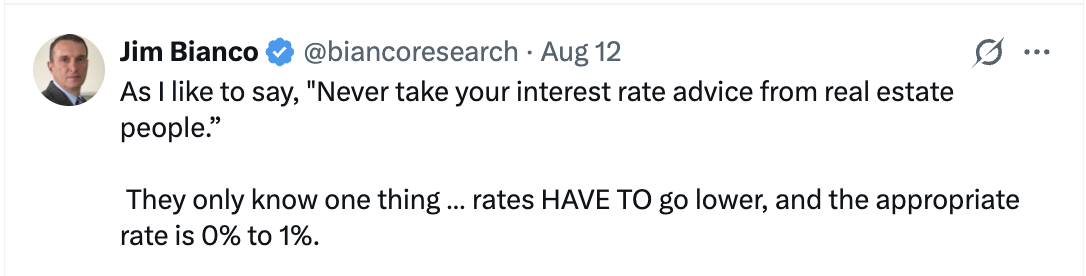
And as I like to say, “Never take your interest rate advice from people that make outlandish claims just to get on CNBC.”
-
October 2023: With the T10 touching 5%, Bianco predicted it would hit “at least” 5.5%. Two months later, it finished at 3.83%.
-
January 2024: Bianco said the T10 would hit 5.5% that year. It peaked at 4.7% and finished the year at 4.38%.
-
January 2025: Bianco said the T10 would average 5.23% for the year. The actual average ended up being 4.3%.
I hope Bianco is calling for the Cowboys to win the Super Bowl.
Last Week This Morning
-
10T: 4.69%
-
2T: 4.17%
-
SOFR: 3.62%
-
Term SOFR: 3.64%
-
CPI as expected and down from last month
-
PPI cooler than expected and also down from last month
-
UMich Consumer Sentiment much worse than expected
-
Retail Sales -0.6% vs. 0.1% expected
-
60% of millennials and Gen Z’ers reported moving back into their parents’ house over the last two years
Inflation? What Inflation?
Headline CPI fell to 3.4% and Core CPI fell to 2.48%, a 5yr low.
The monthly data is considered more important right now. Both monthly measures rebounded after last month’s negative prints, but would still annualize at very low levels.
- CPI: 0.07%
- Core CPI: 0.22%
The next day, PPI came in even cooler. CPI and PPI allow forecasters to very precisely forecast Core PCE, which comes out next week. Following last week’s releases, Core PCE is likely to come in at 0.2% (annualizing at 2.4%).
Odds of a hike in September plunged to 33%, but odds of a hike at some point before year end are still elevated at 67%. We’ll get another CPI/PPI report and another jobs report before the 9/16 meeting, so we aren’t out of the woods just yet.
Remember in March when forecasters from JPM/Citi/Morgan Stanley were saying Brent would blow through $150/barrel if the Strait of Hormuz issue wasn’t resolved quickly? Several months later and Iran saying it won’t negotiate with the US until January 2029, Brent is $88/barrel – a far cry from the $119/barrel in April and not remotely close to $150.
How confident are we that we have an inflation problem?
With any luck, Jim Bianco thinks oil is heading to $200/barrel.
Tap on the Brakes, Don’t Slam on Them
Having taught five kids how to drive, one of the biggest challenges is teaching them smooth acceleration and smooth braking. I got so nauseous. Slamming on the brakes to stop us 10 feet before the line…I’m glad that stage of life is behind me. In what might be the most heavy-handed analogy in newsletter history, I see similar parallels today with those calling for hikes.
First, I am certain Warsh is changing the yardstick. I thought he might propose the Fed mimic the language of the labor mandate (“full employment” rather than an explicit target). He has not done that, and in fact has beaten a dead horse about 2%. So instead, he is changing the measure of 2% from Core PCE to “underlying inflation.” My suspicion is that phrase is intentionally ambiguous, effectively abandoning a numerical target.
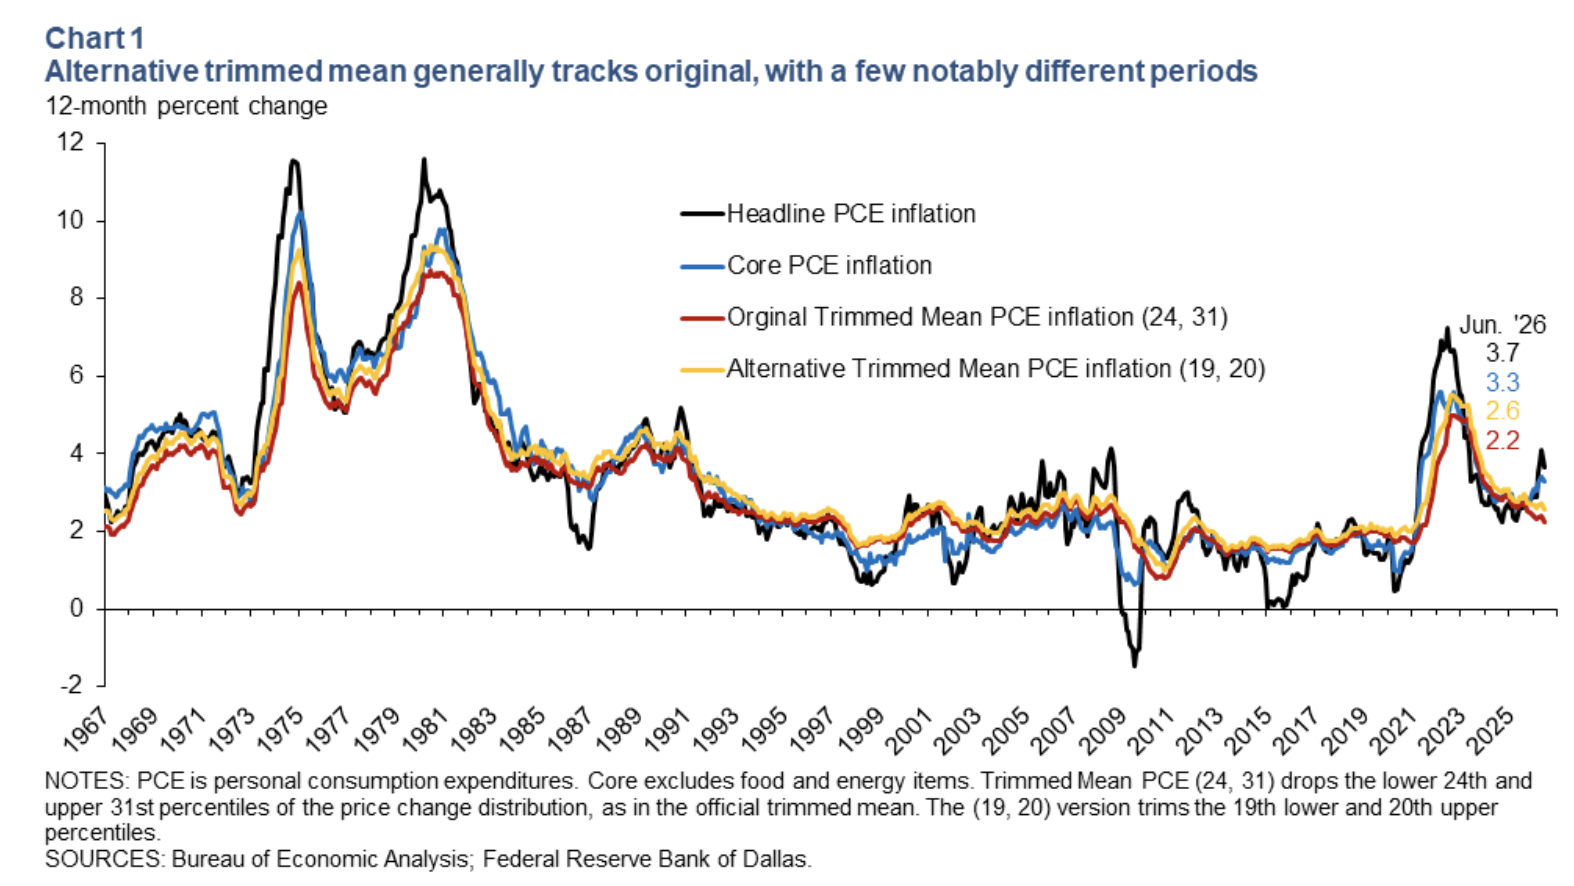
Warsh has repeatedly referenced a trimmed mean inflation measure as an alternative to Core PCE. Don’t be surprised if his inflation task force strongly suggests the Fed consider moving to a more modern version of measuring inflation…which conveniently happens to be lower than Core PCE.
The Dallas Fed publishes this trimmed mean inflation measure and last week they released a revision to more equally balance the removal of the noisiest upside and downside inputs. It increased the trimmed mean from 2.2% to 2.6%...but nowhere close to the 6%+ we saw in 2022.
The Cleveland Fed’s Inflation Nowcast puts Core PCE at 2.9%.
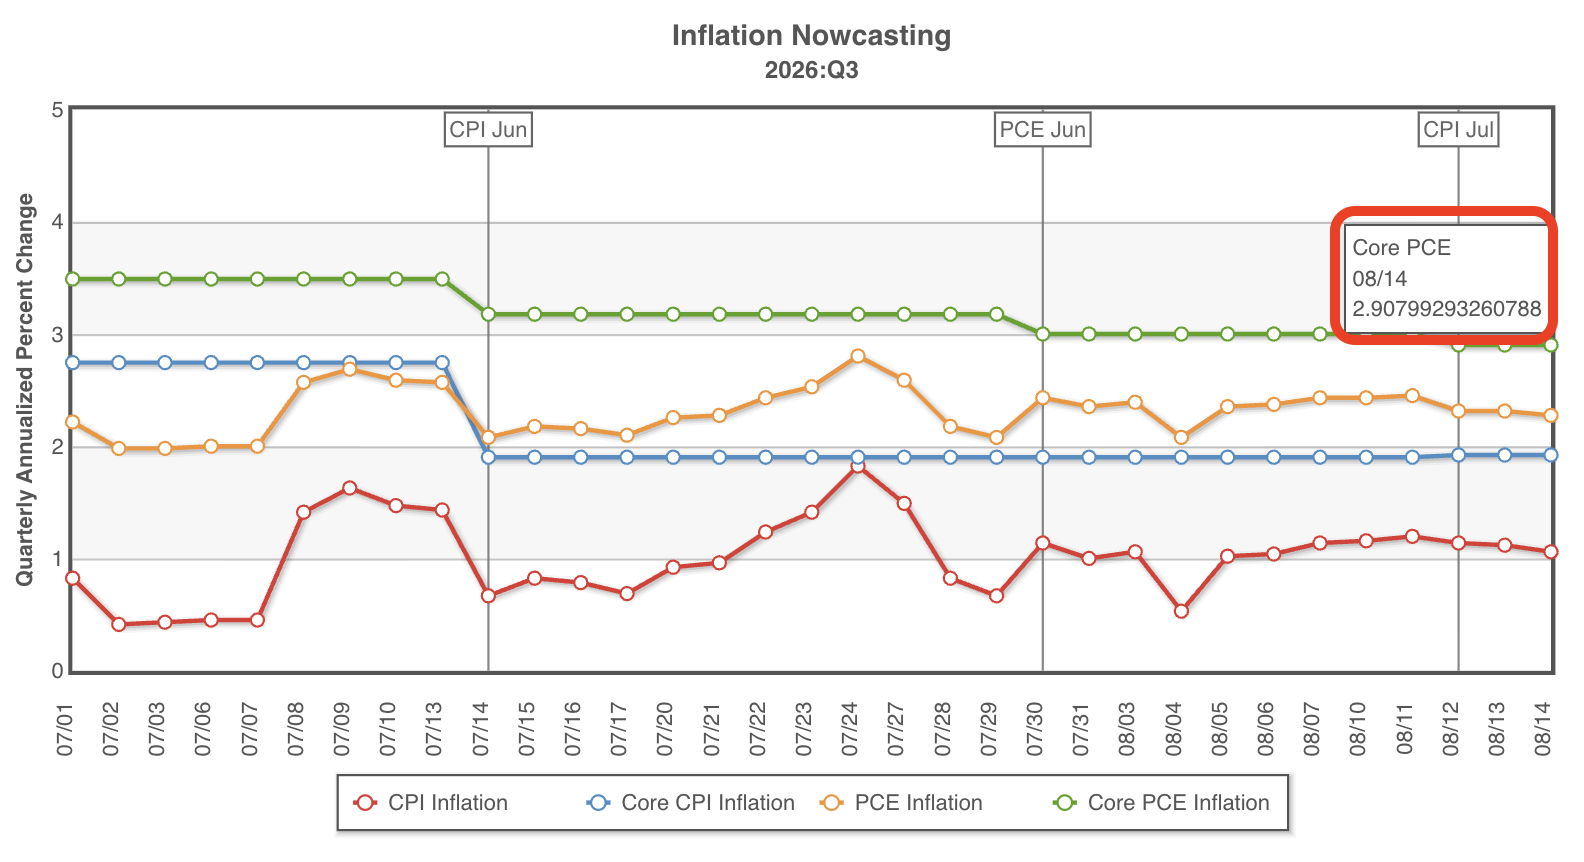
North of 2%, but nowhere close to the 5.5% we saw in 2022.
Money supply is growing, but the question is whether it’s growing faster than the economy can absorb? We don’t know yet, but can we at least agree it’s nowhere close to what we saw in 2022?
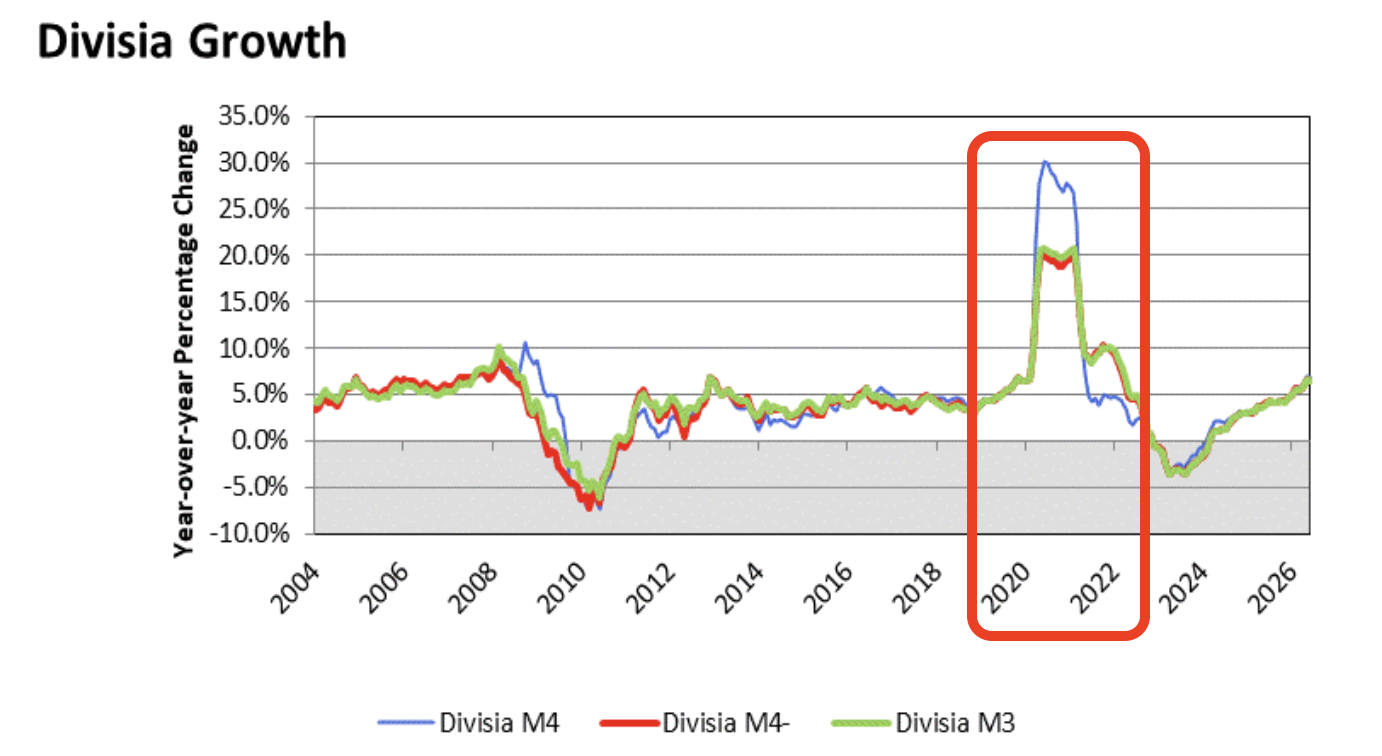
I think the same recency bias that caused me to underestimate inflation in 2022 is leading a lot of people to overestimate it today. The cure for 2022 is not the cure for today.
When you’re doing 95mph in a 55mph zone and see a cop, you slam on the brakes.
When you’re doing 60mph in a 55mph zone and see a cop, you gently tap on them.
I would never ever ever drive 95mph so that is just a hypothetical…
Jobs May Not Be the Focal Point, But They Still Matter
Fed-speak sentiment is highly correlated to the labor market data. As that data initially printed strong in the spring, the Fed started talking up hikes. Now that those numbers have been revised down, the Fed rhetoric about hikes has, too.
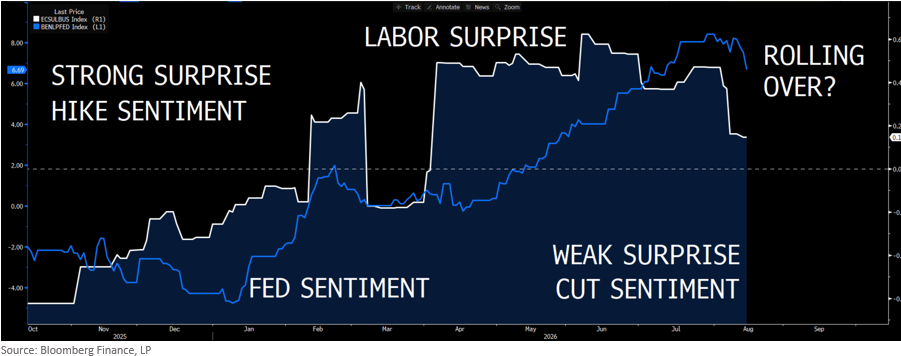
This matters a lot for cap costs. Not just because of the influence on the forward curve, but because removing the threat of hikes helps lower the vol component of a cap cost.
If the jobs data continues to surprise to the downside, Fed-speak should move back towards the dotted line (neutral) and cap costs should move lower with it.
Can Warsh Cancel FOMC Meetings?
The Federal Reserve Act requires the FOMC to meet at least 4x each calendar year. The eight meetings per year is a standard practice, but not the statutory requirement. And since the FOMC has met 5x this year, the question has been raised whether Warsh might simply cancel the remaining meetings.
But Warsh won’t cancel meetings because if 3 voting members of the FOMC call for a meeting, they have a meeting. And Warsh doesn’t get a veto. We had 3 dissents at the last meeting so he would be outvoted the minute he canceled.
The Week Ahead
Pretty slow week ahead. We get the minutes from the last FOMC meeting. Next week will be busier with Core PCE and Jackson Hole.