

GDP, Inflation, and Jobs Oh My!
September 28, 2026
Me after the Fed hiked when I said earlier this year they wouldn’t.
Caleb might be better off playing the other football…
Buckle up, we’ve got a big week and I’m not just talking Birds Bears tonight. Core PCE and jobs and GDP…by 9am Friday, we’ll know if the Fed is hiking in October.
Last Week This Morning
-
10T: 5.16%
-
2T: 4.85%
-
SOFR: 3.88%
-
Term SOFR: 3.89%
-
Fed Speeches:
-
Goolsbee: “The only way to bring inflation down is to raise rates and narrow the gap between supply and demand…Forcing inflation back to target in the short run means pushing employment below target...In the short run, supply shocks force a difficult trade-off.”
-
Williams: “Another rate hike may be appropriate by the end of the year.”
-
Barkin: “Will additional hikes be required, and how many? We’ll see…I’m open to the possibility that inflation could come back down in short order.”
-
Barr: “Inflation is above our 2 percent target and not clearly trending toward target in a timely way. Moreover, risks to achieving our inflation target have increased, while risks to the labor market have receded…Further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion.”
-
Hammack: “It’s real rates that have moved up more than the inflation expectations…We're reasonably well anchored from an inflation expectations perspective.”
-
-
Jordan Love is 1-2 and yet is somehow having a better month than Aaron Rodgers
-
Penn State and Texas A&M are destined for a “You Aren’t Relevant Anymore Bowl,” aren’t they?
Fed Path
The real question is whether it’s 1 hike or > 6 hikes. Unfortunately, since 1990 there’s only been one time when they hiked once - 1997. Every other cycle was at least 150bps. That would give SOFR a 5-handle.
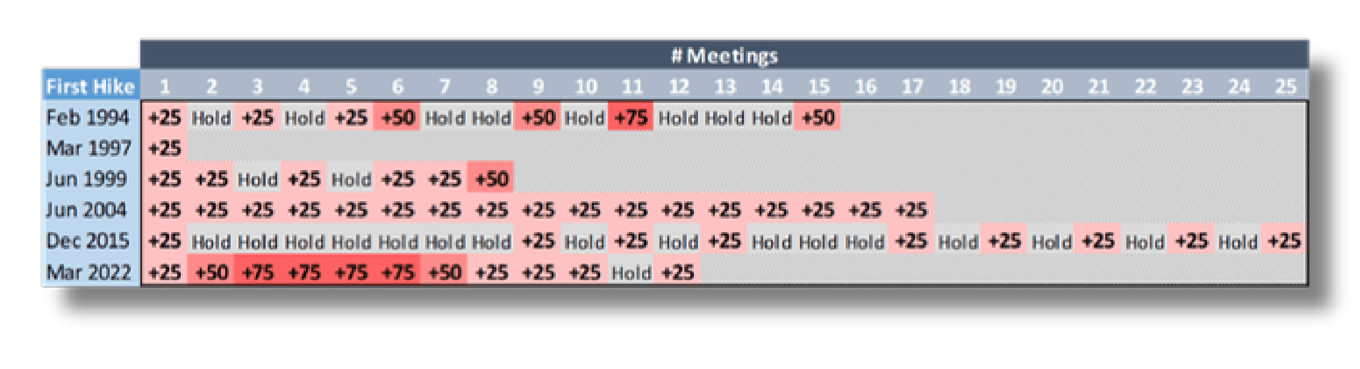
Just as bad, the average time from last hike to first cut is 11 months, which suggests any cuts are Q4 2027 at the earliest. The fastest about face was 5 months in 1995.
Maybe I’m just talking my book, but here’s why I think it will be 3x or less.
Inflation
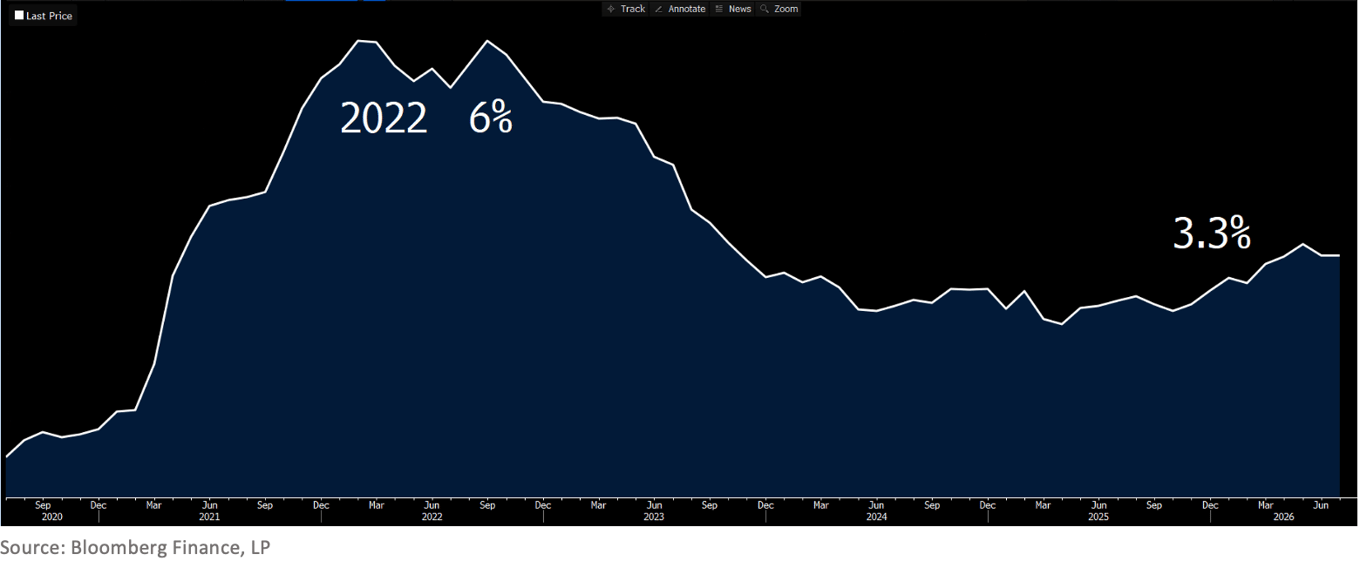
Core PCE is half of what it was in 2022. And as Bill Ackman pointed out last week, the hyperscaler boom that is driving so much of inflation is unlikely to be deterred by higher rates. They believe so completely in AI that guys like Oracle’s Larry Ellison are posting their own stock as collateral to keep moving the ball forward.
Plus, Warsh’s preferred measure of inflation, Trimmed Mean, is just 2.3% (and it’s not like it didn’t reflect higher inflation in 2022). I bet his inflation task force will recommend in December that the Fed should incorporate the Trimmed Mean PCE into its overall policy framework.
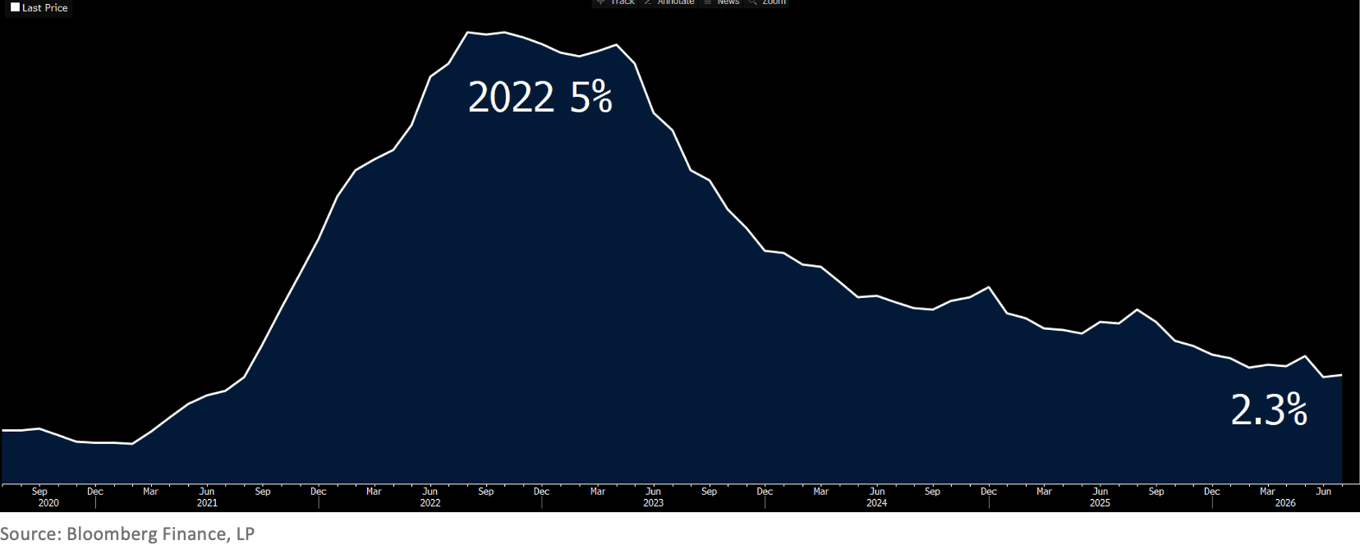
Just because inflation is elevated doesn’t mean it’s the same as it was in 2022.
The prescription dosage should reflect that.
Biggest risk – Iran not only doesn’t get resolved, it actually escalates after the midterms. Oil higher for longer means rates higher for longer. Jay in Dallas is one of the most thoughtful guys I know and has been telling me higher for longer for years. He also is very worried about ground troops in Iran, which would be very bad news. I have learned to listen to Jay.
Jobs
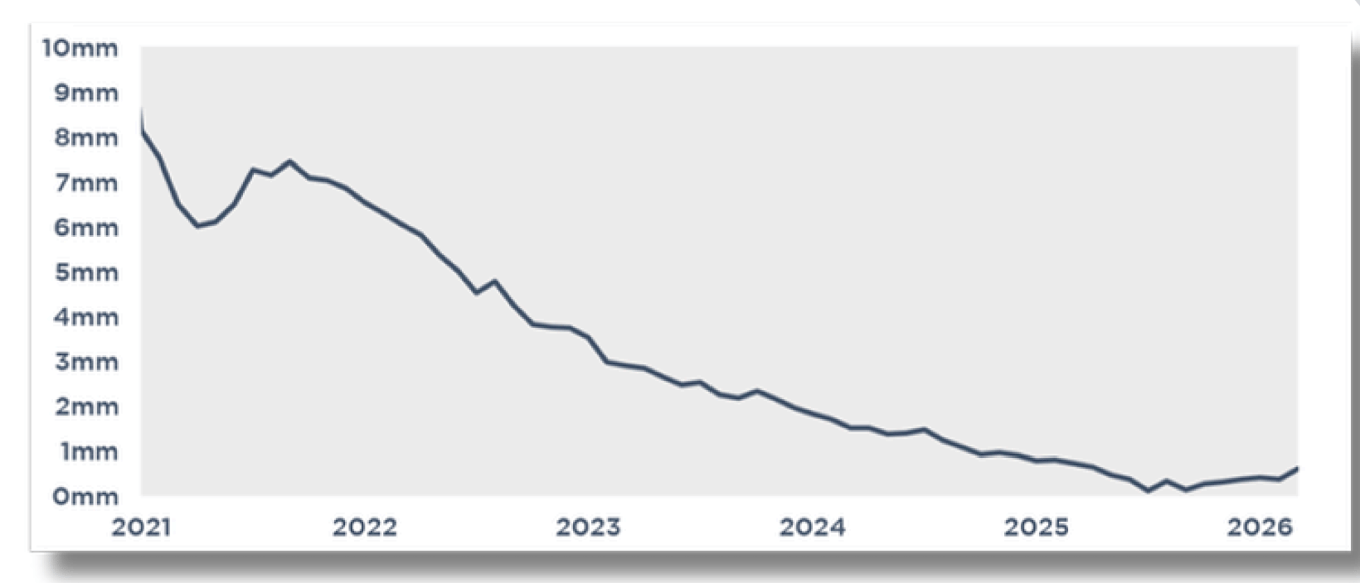
Same as inflation. Not remotely close to where we were in 2022. That year, we averaged 580k jobs per month. In all of last year, we added 508k. This year has already beaten last year’s total, so it’s fair to worry about it reaccelerating. Just keep in mind we are so friggin’ far from 2022 levels we shouldn’t need the same amount of hikes to slow things down.
Money Supply
It’s been a long time since a Fed Chair was obsessed with money supply, so I suspect Warsh will talk about it a lot once/if oil settles down. But if it’s not surging like it did in 2020, will we really need the same monetary policy response?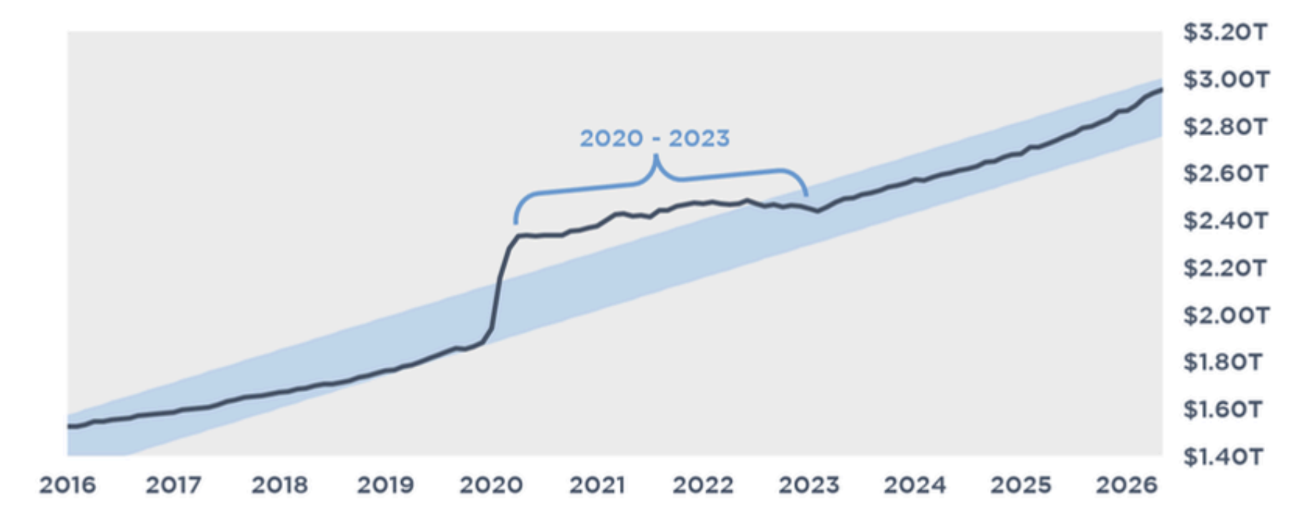
Real Rates
Real rates are already very high. Look at where real rates were in 2021: negative 1%. That’s why we were all so busy. The Fed has way less work to do right now.
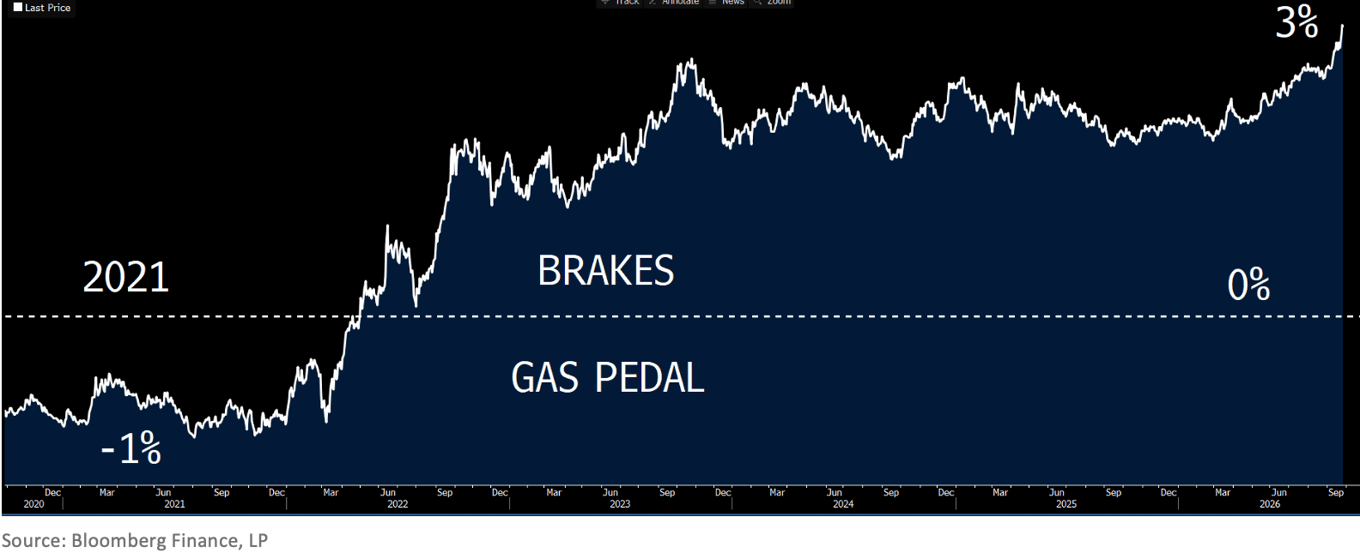
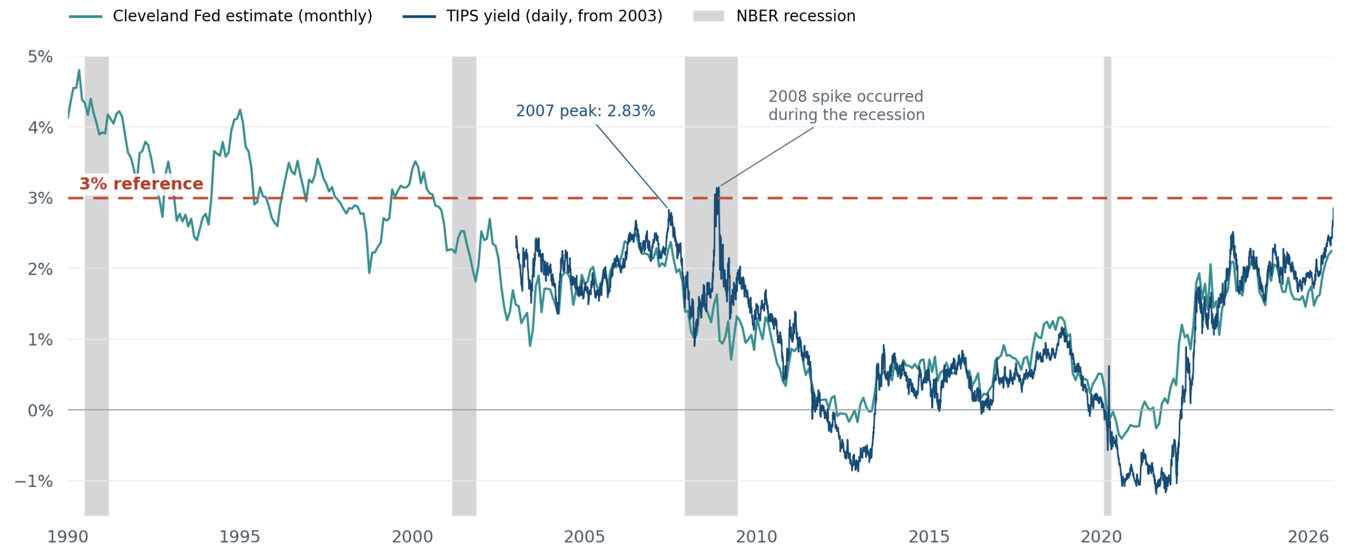
Real rates at 3% have historically been a strain on the economy. Maybe we can absorb them in this cycle, but I would be nervous assuming we can while job creation is so low. I think 3% real rates will contribute to braking action on the economy and the Fed will stop after 2-3 more hikes and let the restriction do its thing.
My Hypothesis
The market has SOFR peaking at 4.79%, but because everyone is on edge, you need to raise the strike to about 5.5%-ish to really drive down the cost meaningfully. That means buying a cap from about 4.5% - 5.5% is the least efficient thing you can do.
Here’s a $100mm 2yr cap with a strike at 4.8% (intentionally 1bp above the market’s peak). You’ll pay $722k in uncertainty premium even though the market thinks this cap won’t provide any protection. Normally, you could raise the strike a little bit and cut the cost in half. But markets are on edge, so you would need to raise the strike to 5.5% just to cut the price in half.
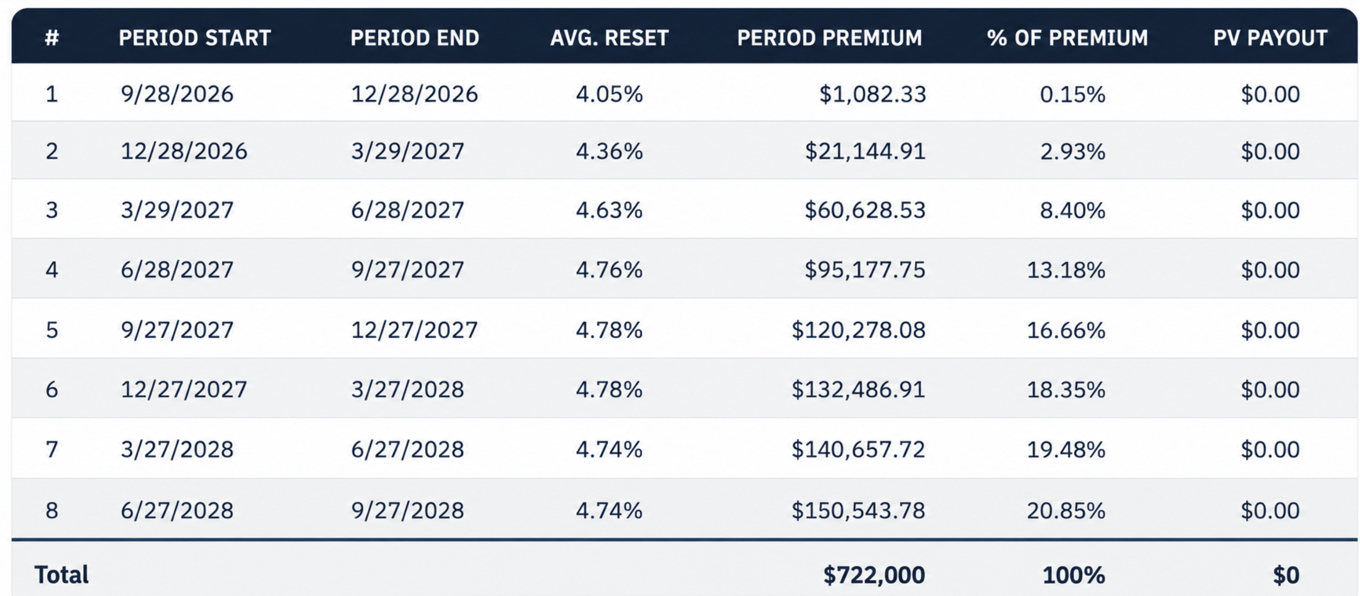
If you’re trying to minimize upfront cost instead of buying in the money strikes, you may need to raise the strike very high. The expected protection from a 4.8% cap is the exact same as a 5.5% cap, but one costs half as much as the other.
If I am right (which I appreciate is a stretch), SOFR won’t exceed 4.50%-ish, and at some point the Fed will level off. Once that ultimate landing spot becomes clear, vol should dissipate from the higher strikes as the market backs out those odds. That’s when I would consider a cap between 4.5% - 5.0%.
P.S. - That analysis is available on our website. It’s definitely the best site in the biz, make sure you are getting your money’s worth out of it!
The Week Ahead
About 8,000 Fed speeches. Core PCE and GDP on Wednesday, and the jobs report on Friday.
One quirk about this week’s Core PCE – it might come in a little better than expected because of a benchmark revision. The market will account for that.