

Fund Level Hedging: Selling Back Caps and Floors
When discussing hedging options, collars and corridors are often common topics of discussion. If you’re not familiar, here’s a quick overview:
-
Collar – buy a cap and sell a floor. The value of the floor offsets the cost of the cap (plus bank profit), often resulting in a “costless” (upfront) transaction. Borrower floats between the cap and floor for the term of the hedge.
-
Corridor – buy a lower strike cap and sell back a higher strike. The upfront premium is lower than a vanilla cap and total flexibility is retained. However, a corridor doesn’t put a true ceiling on rates, so it doesn’t satisfy a lender hedge requirement.
Both strategies seek to offset all or a portion of the upfront cost of a cap, but you’re limited in when you can actually use them.
- Collar – if the underlying lender isn’t a bank with the ability to offer derivatives (debt funds, Agency lenders, life cos.), then you’re likely stuck with a vanilla cap.
- Corridor – if the underlying lender has a hedge requirement, you’re going to need a hedge with a true ceiling (cap, swap, collar).
And now we tie this back to fund level hedging! By leveraging a fund level trade, institutional borrowers are able to sell back floors and caps, assembling collars and corridors on loans where they otherwise wouldn’t be able to.
In both cases, the required cap would still live at the asset level to satisfy the lender’s requirement, and the sold leg at the fund. To help paint the picture, let’s look at two quick examples.
Collar – sell a floor
Hedging for a longer term (2-3+ years) with a cap can become extremely expensive. The sale of a floor recoups all or a portion of the cap premium (depending on the strike), helping reduce or completely offset the upfront expense.
The upside is no (or a reduced) cap premium, and the downside is limited ability to float lower. Consider the following example:
- Purchased cap – assume a 4.50% cap is purchased for 3 years. The upfront cost of this would be 0.80% of notional today.
- Whenever SOFR > 4.50%, the hedge provider pays the borrower the difference between SOFR and the cap strike.
- Whenever SOFR > 4.50%, the hedge provider pays the borrower the difference between SOFR and the cap strike.
- Sold floor – to obtain a cash-neutral transaction, the floor sold would be around 3.90%.
- Whenever SOFR < 3.90%, the Fund owes the hedge provider the difference between the floor strike and SOFR.
- Prefer the floor to be set at 3.50% instead? The transaction would no longer be costless, but a portion of premium could be offset. A buy 4.50% cap / sell 3.50% floor would have an upfront premium of around 0.44% of notional, or roughly half the cost of the vanilla cap.
Below, we’ve included an illustration of the collar
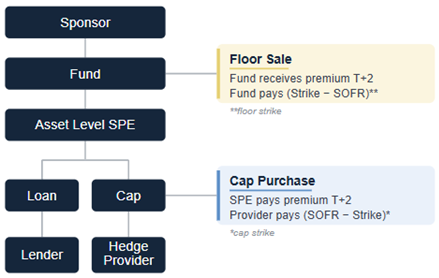
A few things to keep in mind:
- Like a swap, the big risk is MtM exposure. If the floor is terminated early but rates have fallen, there will likely be a breakage due.
- If rates fall, the floor sale prevents borrower from recognizing the benefit of floating lower.
- If your loan already has an index floor, a collar will leave you with two.
Corridor – sell a higher cap
Instead of selling a floor, sell a second cap at a higher strike. You keep the ability to float lower; what you give up is protection above the sold strike.
- Purchased cap – assume a 4.50% cap is purchased for 3 years.
- If SOFR > 4.50%, hedge provider pays the difference between SOFR and 4.50%.
- Sold cap – assume a 6.00% cap is sold for 3 years.
- If SOFR > 6.00%, Fund pays the difference between SOFR and 6.00%.
- Net cost of the trade: 0.54% of notional
Whenever SOFR is at or below 6.00%, it feels like borrower purchased a 4.50% cap for less. Whenever SOFR exceeds 6.00%, the net rate begins increasing and the max net reimbursement is the difference between the two strikes (or 1.50% in this example).
Below, we’ve included an illustration of the corridor.
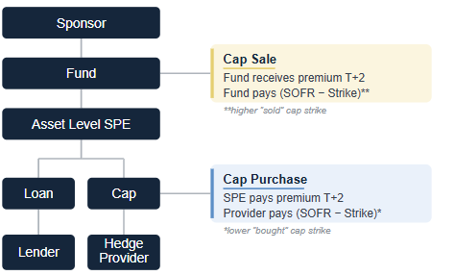
A few things to keep in mind:
- Unlike the collar, the value of the bought cap always exceeds the value of the sold cap, meaning a net positive MtM. If rates have fallen, at worst, both caps have no value.
- Since the structure doesn’t put a hard ceiling on rates, if SOFR spikes dramatically, the net rate paid on the loan will increase. If SOFR resets at 8.00%, the net rate paid under the example structure is 6.50%, or 2.00% above what a vanilla cap would have resulted in.
- Corridors work by recouping on the volatility component of a cap cost. Therefore, longer terms (2-3+ years) or extremely volatile rate environments produce the most meaningful reduction of the upfront cost.
In Closing
Selling back a cap or floor is one of the most common ways to make longer term protection affordable, as long as you’re comfortable with what you’re giving up.
To be eligible for these strategies, the Fund would need to be underwritten and onboarded by a bank that’s a swap dealer. In some cases, the hedging can be done fully unsecured, but other times a written guaranty, high threshold CSA, collateral posting, or some other arrangement may be required in order to secure the exposure. Requirements vary based on the sponsor, Fund financials, type of hedges targeted, relationship, etc.
Leveraging the Fund to execute other hedge strategies comes with risk, but also provides the ability to pay over time, reduce upfront costs, and/or execute longer term hedging strategies more efficiently. We’re happy to provide additional thoughts and analysis to further weigh the risks and benefits.
Interested in leveraging your fund or weighing other strategies for an upcoming financing? Give us a call at 704-887-9880, email us at pensfordteam@pensford.com, or respond directly.