

Fund Level Hedging: Forward Starting Swaps
A forward starting swap is when a borrower locks a rate today for a hedge that begins in the future. One might do this to take advantage of a dip in rates, or to simply remove risk from the table ahead of a loan closing or hedge maturity.
Most banks will only let you swap ahead of closing if you post cash collateral to secure the exposure. In addition to the burden of posting, the onboarding process can take 1-2+ weeks, which might just defeat the purpose of trading early.
Executing at the fund level often removes these hurdles, and it might be one of the most beneficial use cases we consistently see. With that in mind, this week we continue our fund level hedging series by touching on forward starting swaps.
How it works
The process has two primary steps.
Step 1 – Hedge Execution
We’ve assumed your fund has already been onboarded with a hedge provider (“The Provider”). While it would be nice if the bank facing the fund is also the future lender (“The Lender”), it doesn’t necessarily have to be that way. We’ll assume The Provider and The Lender are the same for now.
-
Hedge structure is selected
-
We notify The Provider of the desired hedge structure and timing
-
The Provider obtains credit approval
-
Once credit approval is received, a swap lock call is held
If all goes as planned, this process can be effectuated inside of 24-48 hours. Same day in some cases.
Step 2 – Hedge Novation
In the meantime, the borrowing entity is onboarded with The Provider.
-
At closing, The Provider novates the hedge from the fund to the asset level borrower
-
If any tweaks need to be made to the hedge (notional amount, effective/maturity dates, credit charge), those are made at this time
That’s it. You locked at the fund and novated to the borrowing entity at closing. You hope rates didn’t go down so there’s no buyer’s remorse, but you also hope rates didn’t go up, because that means rates went up!
Here’s a simple visual of the process.
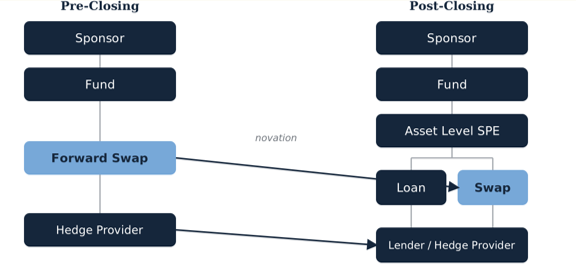
I previously mentioned we’d assume The Provider and The Lender are the same. This is ideal because it’s just a paperwork process to move the swap from the fund to the borrower, and there are no outside parties.
If The Provider and The Lender aren’t the same, it’s not necessarily a big deal. It just adds an extra layer of complexity because (i) The Provider will need to novate the swap to The Lender at closing, and (ii) The Lender will then need to novate the swap to the asset level borrower (step 2 above).
From the borrower’s perspective, moving the swap from one bank to another is also just a paperwork process. However, it’s important to ensure two things:
- The Provider and The Lender have active trading lines in place
- They are both willing and able to face each other on the novation
Without both boxes checked, the forward swap might have to be terminated at closing instead. While this is no problem if rates rose and the swap has a positive value, if rates fell, a breakage would be due.
What’s the risk?
A forward starting swap has no upfront cost, but there’s a tradeoff when compared to alternatives like a swaption. The primary risk is related to the MtM – if the deal falls through and rates have fallen, you’re on the hook for a breakage. That’s why most groups only forward lock when the closing is close to a sure thing, or the swap is tied to an extension or refi that’s highly unlikely to fall through.
While it’s true the swap could theoretically remain at the fund, most banks will include a Termination Event in the confirmation to put a backstop in place. For instance, the fund might have 90 days to novate the trade to another bank or for the obligations to be secured pari passu (in the event The Provider is The Lender).
We’ll keep walking through the possibilities of fund level hedging next week.
Interested in leveraging your fund or weighing other strategies for an upcoming financing? Give us a call at 704-887-9880, email us at pensfordteam@pensford.com, or respond directly.